
South African mountain bikers will deliberate over carbon frame layups, intuitive suspension performance and tyre compounds until the sun goes down. Then most of them get into something remarkably ordinary and drive home. That is the clearest signal in TREAD Media’s annual South African Mountain Biking Survey, presented by Garmin. Of 2 504 respondents in the 2025 edition, 50.16% named one of three brands as their primary vehicle. One in two riders. In a sport defined by specialist equipment, the driveway is strikingly conventional.
Compiled by Sean Badenhorst
The survey cannot prove why riders buy what they buy. Price, reliability, residual value, dealer coverage and family practicality all matter more than a logo on a race banner. What the data can show is the pattern: four years of consistent concentration at the top, a widening gap between the leaders and everyone else, and a community that treats the bicycle as the passion and the car as the logistics platform that makes the passion possible.
THREE BRANDS OWN THE DRIVEWAY
In 2025 the ranking was unambiguous:
- Toyota: 24.81%
- Ford: 13.77%
- Volkswagen: 11.58%
Nissan (4.45%) and Suzuki (4.33%) completed the top five. BMW (4.04%), Land Rover (3.79%), Audi (2.76%) and Mercedes-Benz (2.39%) all appear – proof that premium metal is in the mix — but none of them is within shouting distance of the top three. The concentration is the story. Toyota, Ford and Volkswagen together account for half the sample. The next seven brands combined still do not match Toyota alone.
Here are the full results from the past four years:
What motor vehicle brand do you drive? If more than one, choose the primary brand and add the other into the Other comment box.
| 2025 | 2024 | 2023 | 2022 | |
|---|---|---|---|---|
| Toyota | 24.81% | 22.37% | 22.60% | 22.34% |
| Ford | 13.77% | 13.63% | 13.73% | 14.34% |
| Volkswagen | 11.58% | 13.11% | 15.86% | 12.25% |
| Nissan | 4.45% | 3.89% | 4.09% | 5.18% |
| Suzuki | 4.33% | 3.68% | 4.22% | 2.81% |
| BMW | 4.04% | 3.99% | 3.96% | 4.28% |
| Land Rover | 3.79% | 3.45% | 3.79% | 3.53% |
| Audi | 2.76% | 3.04% | 3.83% | 3.56% |
| Hyundai | 2.56% | 3.04% | 3.41% | 3.43% |
| Mercedes Benz | 2.39% | 2.42% | 2.68% | 3.39% |
| Mitsubishi | 2.31% | 2.35% | 2.17% | 2.40% |
| Isuzu | 2.23% | 2.32% | 2.08% | 2.12% |
| Volvo | 2.14% | 1.40% | 2.17% | 1.54% |
| Subaru | 1.94% | 1.70% | 1.66% | 1.78% |
| Mazda | 1.90% | 2.01% | 2.04% | 2.19% |
| Renault | 1.81% | 2.42% | 2.77% | 2.26% |
| Kia | 1.57% | 2.15% | 2.21% | 2.12% |
| Honda | 1.57% | 1.53% | 1.36% | – |
| GWM | 1.44% | 0.58% | 0.68% | – |
| Mahindra | 1.15% | 0.78% | – | – |
| Chery | 1.11% | 0.75% | 0.59% | – |
| Chevrolet | 1.07% | 0.75% | 1.23% | 1.57% |
| Haval | 0.99% | 1.09% | 0.98% | 0.92% |
| Porsche | 0.66% | 0.88% | 0.68% | – |
| Jeep | 0.62% | 1.09% | 1.10% | 0.89% |
| Other | 3.01% | 5.46% | 4.95% | 7.00% |
TOYOTA IS NOT WINNING A SEASON; IT’S HOLDING A CATEGORY
Toyota’s 24.81% share is not a one-year spike. It has finished comfortably first every year since we first asked the question:
- 2022: 22.34%
- 2023: 22.60%
- 2024: 22.37%
- 2025: 24.81%
After three years locked in the low-22s, Toyota moved to almost one in four respondents. That is a commanding position in any consumer survey. In a niche of demanding, brand-aware riders, it is exceptional.
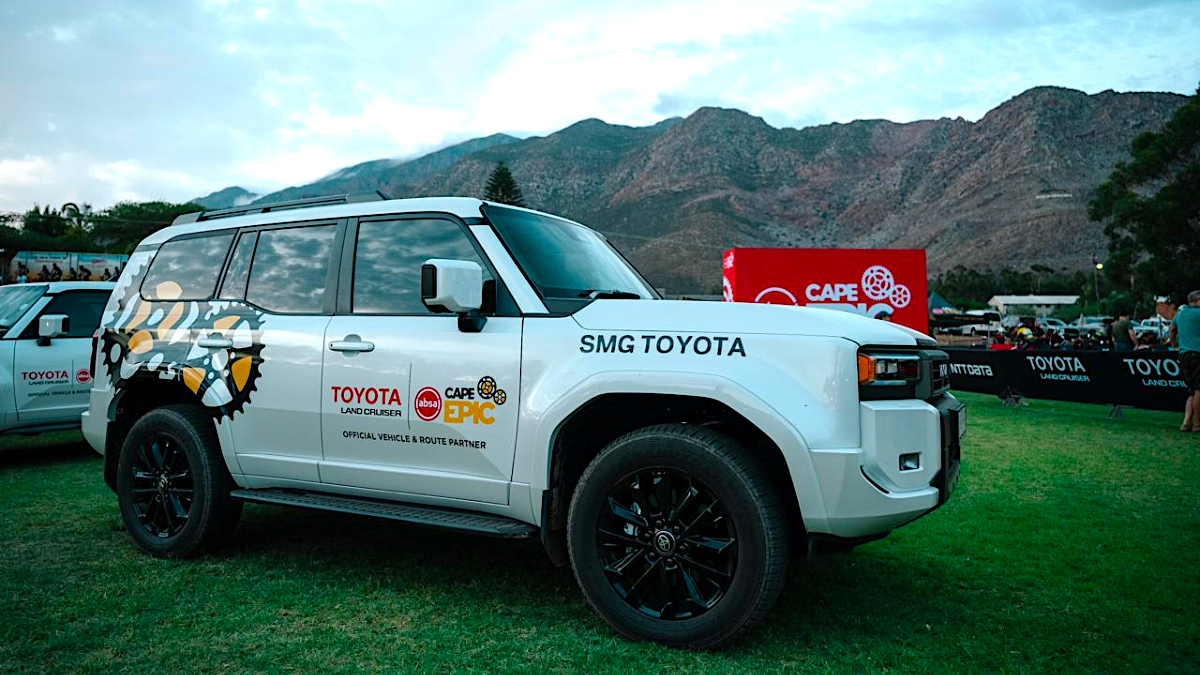
Toyota’s cycling footprint is unusually broad. Toyota is the official vehicle and route partner of the Absa Cape Epic and FNB Wines2Whales until 2028, backs elite racing through the Toyota Specialized Umbuko team, and is official vehicle partner of the Nedbank Gravel Burn gravel race. It also maintains a long-running media presence through the Toyota Cadence TV programme on SuperSport. That is coverage across elite MTB, mass participation, gravel and a weekly broadcast.
The survey does not isolate how much of the 24.81% is attributable to that involvement. It does show something harder to dismiss: Toyota’s cycling audience and its vehicle customer base overlap at scale, year after year.
FORD’S SECOND PLACE IS STABLE
Ford’s share has barely moved:
- 2022: 14.34%
- 2023: 13.73%
- 2024: 13.63%
- 2025: 13.77%
That consistency matters. Ford is title sponsor of the Trailseeker Series, one of the country’s largest mass-participation mountain-bike platforms, after first supplying vehicles to the series. The brand also backs elite racing through the Ford Prime Bunch men’s team and co-sponsorship of Insect Science and Safari Essence Elite racing teams.
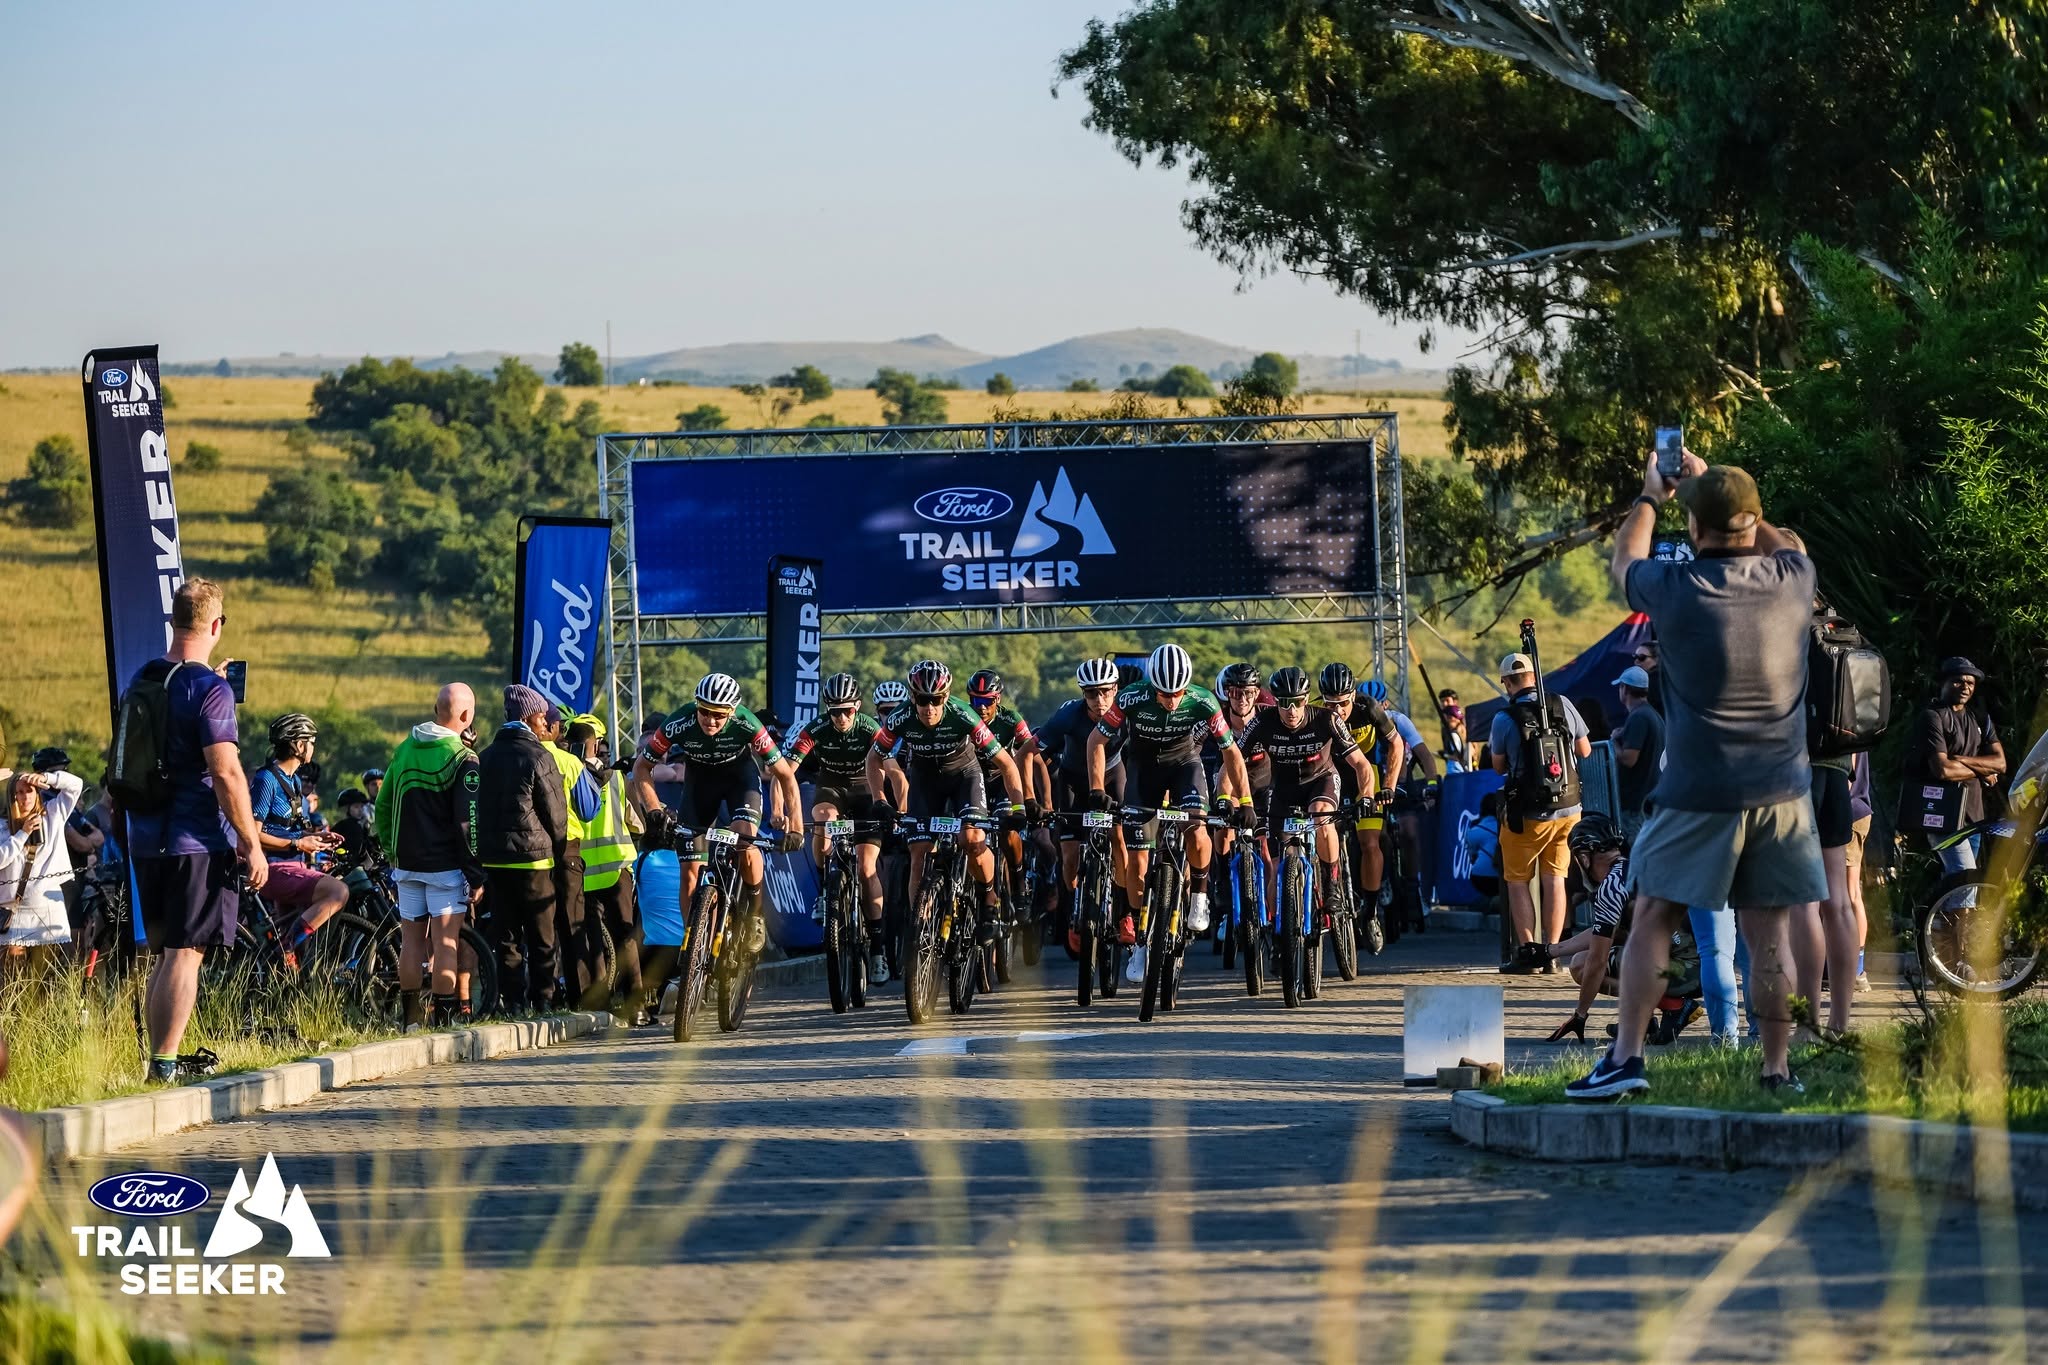
Again, correlation is not causation. A Ranger or Everest is an obvious fit for a sport that needs tow bars, load space and long-distance reliability. Ford’s cycling presence simply sits on top of a product range that already matches the use case. It is the market behaving rationally.
VOLKWAGEN’S RESULT IS THE INTRIGUING ONE
Unlike Toyota and Ford, Volkswagen has no equivalent mountain-bike sponsorship architecture and it still finished third at 11.58%. The trend line is less flattering. VW was second in 2023 at 15.86%, third in 2024 at 13.11%, and third again in 2025 at 11.58%. The brand remains inside the leading group, but it is the only member of that group losing mountain biker market share in a straight line.
That is the most useful reminder in the data. Sponsorship can amplify preference. It does not create it on its own. Price, product mix, residual values, urban practicality and brand familiarity still decide a large share of purchases.
THE REST OF THE MARKET IS FRAGMENTED
Below the top three, the field breaks apart quickly. Nissan and Suzuki are the only other brands above 4%. And, while (barring Ford) South African mountain bikers are still primarily choosing Japanese and German motor brands, Chinese and associated newcomers remain small individually, but they are no longer invisible: GWM (1.44%), Mahindra (1.15%) and Chery (1.11%) are all on the board, and GWM in particular has more than doubled from 0.58% in 2024.
Premium brands tell a different story. BMW, Land Rover, Audi, Mercedes-Benz, Volvo and Porsche collectively prove that some riders will spend up. None of them threatens the mass-market leaders. In this community, status in the garage is secondary to getting the bikes, the people and the weekend kit to the start line or trailhead.
WHAT THE FOUR-YEAR RECORD ACTUALLY SAYS
TREAD has now asked this question long enough for the pattern to harden:
- Toyota is the default brand of South African mountain biking, and its lead widened in 2025.
- Ford holds a durable second place, aligned with both product fit and a major series sponsorship.
- Volkswagen remains a top-three brand without a comparable MTB platform, even as its share declines.
- Premium and emerging brands populate the long tail, but they do not break the dominance at the top.
The honest conclusion is unsentimental. South African mountain bikers are not shopping the car park for a statement. They are shopping for a tool. Toyota, Ford and Volkswagen are winning because they look, to this audience, like the tools that offer the best service.
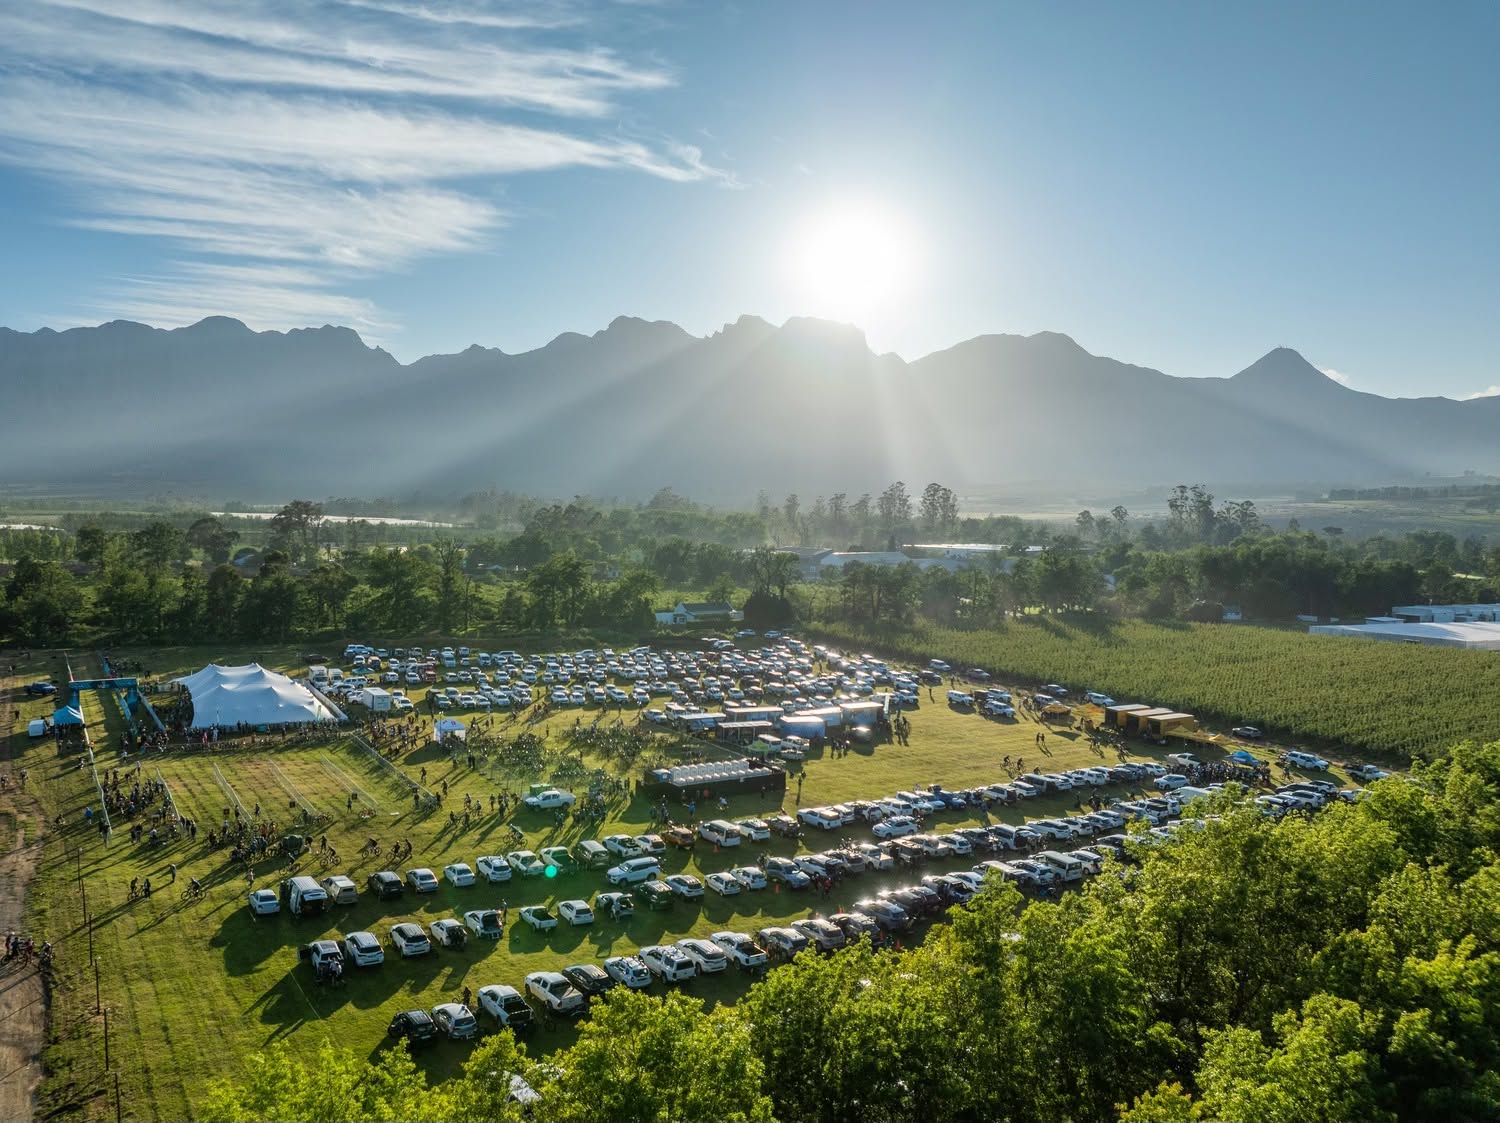
Intro photo: Standard Bank Berg & Bush
MORE SOUTH AFRICAN MTB SURVEY ANALYSIS ARTICLES

